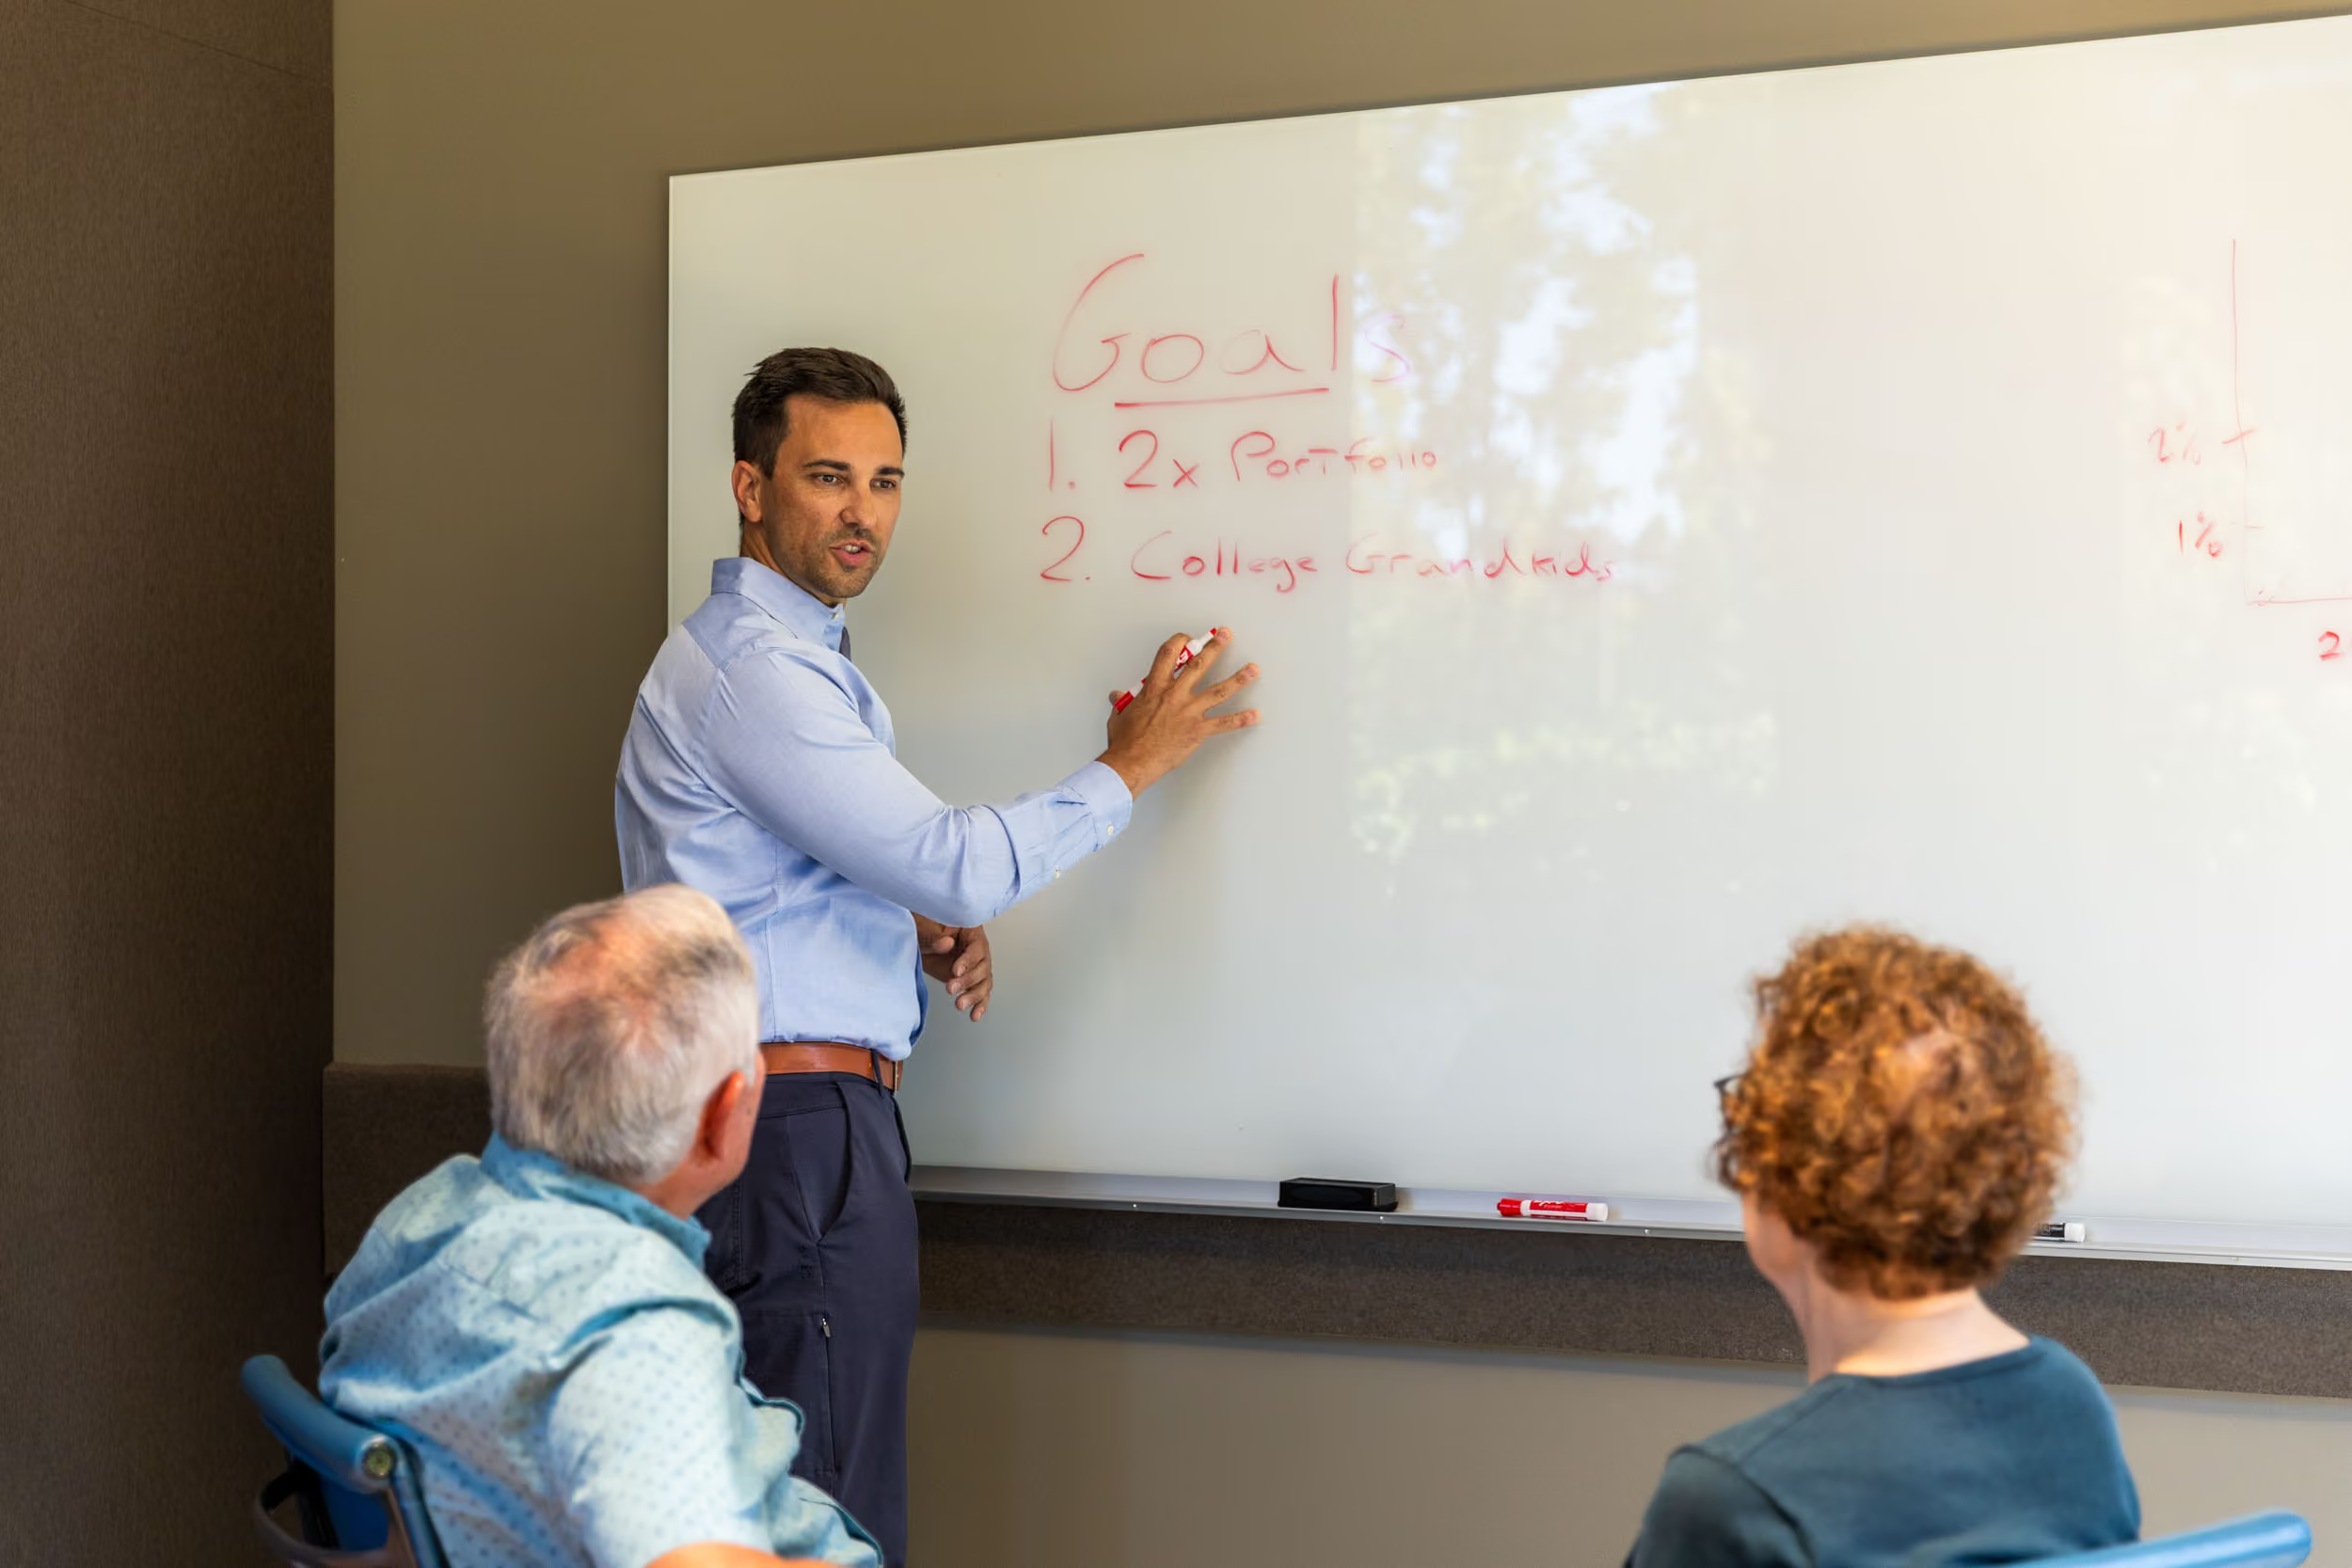
What does financial independence mean for my family?
Financial independence means your income no longer depends on a paycheck. For many Christian families it also means freedom to serve, give and spend time with people. Your plan starts with that purpose, then adds numbers.
Seek First describes retirement planning as creating a strategy that leads to your financial independence. The first step is not a spreadsheet. It is a conversation about your values, goals and priorities. That is the first item the firm lists under Retirement Planning: “Clarify your values, goals, and priorities.”
Some questions to answer before any math:
- What do you want to do with your time at 60, 70 and 80?
- Where do you want to live, and near whom?
- What do you want to give, and to which churches or ministries?
- What do you want to leave to children or to the Lord’s work?
- Who needs your help now, such as aging parents or adult children?
Your answers set the target. Two couples with the same savings can have very different plans. One may want to work part time at a ministry. Another may want to give a large share of income each year. The plan should fit your calling, not a generic chart.
How do I know if I have enough?
You have enough when your income sources cover your spending, taxes, health care and giving for the years you expect to live. Add up what comes in, subtract what goes out, and test the gap against a range of outcomes.
Here is a simple way to frame it:
- Write down yearly spending. Include housing, food, travel, family help and health care. Add what you plan to give.
- List income that arrives no matter what. Social Security, a pension and rental income often belong here.
- Find the gap. Spending plus taxes, minus steady income, is what your savings must supply.
- Test the gap. Run the plan with lower markets, higher inflation and longer life. See where it bends.
- Decide what flexes. Travel, gifts and a home sale can move if needed.
A plan like this does not promise a result. It shows you how your choices change the odds of success and where the weak points sit. Seek First lists “Create and maintain your lifetime financial plan” as part of Retirement Planning, and notes that its lifetime plan, retirement planning and reporting run on eMoney. You review the plan on a schedule and when life changes. A job change, an inheritance or a health event can all move the numbers.
Two risks deserve special attention. Read about sequence of returns risk, which is the danger of poor markets in the first years of withdrawals. Read about investable assets if you wonder which accounts count toward a financial plan. Your CPA and your planner should both look at them.
How do I turn savings into retirement income?
Turning savings into income means choosing which accounts to draw from, in what order, and how much per year. Taxes, required withdrawals and your other income decide the order. No withdrawal rate is promised to last.
You may hear a rule of thumb for a yearly withdrawal rate. Rules of thumb start a conversation. They do not replace a plan. Read the glossary entry on withdrawal rate rules of thumb to see why. Markets, taxes and your age at retirement change the answer.
Most families hold money in three kinds of accounts. Each is taxed differently.
| Account type | Examples | How withdrawals are usually taxed |
|---|---|---|
| Pre-tax | Traditional IRA, 401(k) | Ordinary income when you withdraw |
| Taxable | Brokerage account, savings | Interest, dividends and gains in the year they occur |
| Roth | Roth IRA, Roth 401(k) | Qualified withdrawals are usually tax free |
The order you use these accounts can change your lifetime tax bill. A common planning question is whether to draw taxable money first, pre-tax money first, or a mix. The answer depends on your brackets now and later, your required withdrawals and any plan to leave money to heirs or charity. A Roth conversion in a low-income year is one tool to review with your CPA. The guide on Roth conversion questions lists what to ask first.
Where you hold each investment also matters. That topic is called asset location. Seek First manages investments as part of the plan so the account order and the holdings work together.
For a deeper walk-through of the order of withdrawals, read the guide on retirement income, RMDs and Social Security.
What are RMDs and when do they start?
A required minimum distribution (RMD) is the least you must take from a pre-tax retirement account each year once you reach a set age. The IRS says that age is generally 73. Missing an RMD can bring a 25% excise tax.
Here is what the IRS page says: “You generally have to start taking withdrawals from your IRA, SIMPLE IRA, SEP IRA, or retirement plan account when you reach age 73.” The page also gives the first deadline as April 1 of the year after the year you reach that age.
The age has changed more than once in recent years. Check the rule for your birth year with your CPA before you rely on the number here. Read the glossary entry on required minimum distribution for the plain definition.
| Question | What the IRS says |
|---|---|
| Which accounts have RMDs? | IRA, SIMPLE IRA, SEP IRA and employer retirement plan accounts |
| When do they start? | Generally at age 73 |
| First deadline | April 1 of the year after the year you reach that age |
| Penalty for missing one | An excise tax of 25% of the amount not taken (10% if withdrawn within 2 years) |
RMDs matter for planning because they are taxable income that you do not control. A large pre-tax balance can push you into higher brackets and raise what you pay for Medicare. Planning in your 60s, before RMDs start, gives you more choices. You might convert part of an IRA to Roth in lower-income years. You might also decide to give from the IRA.
If you give to your church, there is a direct route. A qualified charitable distribution sends IRA money straight to a charity. Per IRS Publication 526, “You must have been at least age 70½ when the distribution was made.” It may be nontaxable, but then you cannot also deduct it. Ask your CPA how it works with your RMD. Read the glossary entry on qualified charitable distribution and the guide to qualified charitable distributions. Rules and dollar caps change by year, so confirm the current figure.
How do taxes, Social Security and Medicare fit together?
They fit together through your income. What you withdraw from savings can make more of your Social Security taxable and can raise your Medicare premiums. Plan the three as one system, not in separate steps.
Social Security. The Social Security Administration says you can start your retirement benefits “as early as age 62.” Your benefit is reduced for each month you claim before full retirement age. SSA also says that if you delay from full retirement age up to age 70, your benefit amount will increase.
Claiming is a personal decision. Health, marital status, other income and plans for work all matter. A spouse who outlives the other may keep the larger benefit, so couples often look at claiming as a joint choice. Read about Social Security claiming strategy.
Taxes on benefits. SSA says you will pay federal income tax on benefits if combined income “exceeds $25,000/year filing individually or $32,000/year filing jointly.” Where you withdraw from IRAs affects that combined income. California is different. The Franchise Tax Board states that “California law differs from federal law in that California does not tax: • Social security benefits.” That FTB publication is from 2021, so confirm with your CPA.
Medicare. Medicare says you are first eligible for Part A and Part B “starting 3 months before you turn 65 and ending 3 months after the month you turn 65.” Sign-up rules differ if you or your spouse still work and have job-based coverage. Late enrollment can bring a penalty, so check your dates early.
Premiums and income. Medicare calls the extra premium for higher earners IRMAA. The 2026 Medicare cost fact sheet sets Part B premiums by “yearly income in 2024.” That means a large Roth conversion or stock sale can raise premiums two years later. Read about IRMAA before you plan a big income year.
| Decision | What it touches |
|---|---|
| When to claim Social Security | Lifetime benefit, survivor income, taxes on benefits |
| When to sign up for Medicare | Coverage start date, possible late penalties |
| IRA withdrawals and conversions | Tax bracket, taxable Social Security, Medicare premiums |
| Giving from the IRA | Taxable income, RMD amount |
This is why a lifetime plan and tax planning belong together. Read more about tax planning at Seek First. Seek First lists “Help you make confident decisions on major life events” as part of Retirement Planning, which includes choices like these.
How does retirement fit my calling and giving?
Retirement can be a time to give more, serve more and teach more. A good plan sets aside money for those goals first, then tests whether the rest of your income covers your needs.
Scripture speaks about work, rest and generosity. Luke 12:48 teaches that those who receive much carry greater responsibility, and the client puts it this way: “To whom much is given, much is required.” Proverbs 13:22 speaks of leaving an inheritance to children’s children. Read these as prompts to think, not as a formula. Families apply them in different ways.
Practical questions to bring to your planner:
- How much do you want to give each year, and to whom?
- Will you give cash, appreciated stock or IRA money?
- Do you want to set up a donor-advised fund for giving over several years?
- Do you want gifts to continue after you die, through a trust or a bequest?
- How will your gifts change your taxes and your income plan?
Seek First treats generosity as part of the plan. The firm’s Generosity and impact work includes “Create strategies to maximize your impact” and “Manage gifting of assets.” For the whole topic, see charitable giving strategy. For the Biblical side of giving, see biblical stewardship.
Retirement also changes your estate plan. Your documents should name who handles money if you cannot, who receives what, and which causes you want to support. See trust and estate planning for how that fits.
How does Seek First plan for retirement with families?
Seek First builds a lifetime financial plan with you and coordinates the people who touch it. The firm says it serves as your financial CEO, so your investments, tax strategy, insurance and legal documents move in step.
The firm describes the problem plainly: “When you have to coordinate an investment advisor, an outside CPA, an estate attorney, and an insurance agent, critical details get lost and strategies fall out of sync.” Seek First puts that team under one roof. The Retirement Planning service lists four things it does for you:
- Clarify your values, goals, and priorities
- Create and maintain your lifetime financial plan
- Help you make confident decisions on major life events
- Manage your investment accounts
The firm states that it is a fiduciary: “Yes. We are legally and ethically bound to act as your fiduciary, meaning your interests must always come before our own.” The firm also notes that “Investing involves risk of loss.” Nothing on this page is a promise of results. This page is general education and is not tax or legal advice. Ask your own CPA or attorney about your situation.
Retirement planning is one of six services. The others are Tax Strategy & Filing, Investment Management, Trust & Estate Planning, Risk Management and Impact Planning. Read about all six on the how we serve page. If you want to know whether Seek First fits your family, read the FAQ or the guide to choosing a Christian financial advisor.
Next step
Start with a free 20-minute call. We will talk about your goals and what a retirement plan should cover for your family. Schedule a free call or phone (866) 398-4044. You can also read how the five stewardship gaps show up in retirement, or see all services on how we serve.
Frequently asked questions
How much money do I need to retire?
There is no single number. Start with what you spend each year, subtract guaranteed income such as Social Security, and add taxes, health care and giving. The gap is what your savings must cover. A written plan tests that gap against different ages and markets, and you update it as life changes.
At what age do required minimum distributions start?
The IRS says you generally must start taking withdrawals from your IRA, SIMPLE IRA, SEP IRA or retirement plan account at age 73. The law has changed before, so check the rule for your birth year with your CPA. Your CPA can confirm which of your accounts have RMDs.
When should I claim Social Security?
You can start as early as age 62, but your benefit is reduced for each month before full retirement age. If you wait from full retirement age up to age 70, the benefit grows. The right age depends on your health, your spouse, your other income and your taxes.
When do I sign up for Medicare?
Medicare says you are first eligible to sign up for Part A and Part B starting 3 months before you turn 65 and ending 3 months after the month you turn 65. If you still work and have job-based coverage, different rules apply, so check before you delay.
Can I keep giving to my church in retirement?
Yes. Many families give from savings in retirement. A qualified charitable distribution lets people age 70½ or older send IRA money straight to a charity, and it may be nontaxable. Ask your CPA how it fits your situation and your RMD.
Does Seek First guarantee my retirement income?
No. No one can promise investment results or a fixed income from investments. Investing involves risk of loss. Seek First builds a lifetime plan, shows you how it holds up under different assumptions, and reviews it with you as your life and the law change.
Terms on this page
Sources
- IRS: Retirement topics - Required minimum distributions (RMDs)
- IRS: Retirement topics - Required minimum distributions (RMDs), penalty
- SSA: Retirement Age and Benefit Reduction
- SSA: Retirement Age and Benefit Reduction, delayed benefits
- SSA: Request to withhold taxes
- Medicare.gov: When can I sign up for Medicare?
- Medicare.gov: Part B late enrollment penalty
- Medicare.gov: How to pay Part A and Part B premiums
- Medicare.gov: 2026 Medicare costs
- IRS: Publication 526, Charitable Contributions
- IRS: Publication 526, QCD age rule
- FTB: Publication 1005, Pension and Annuity Guidelines
Written by Seek First and checked against the sources above on November 10, 2026. Tax limits, ages and laws change. This page is general education, not tax, legal or investment advice. Please consult legal or tax professionals about your own situation. Investing involves risk of loss.
